Summary
Learning how to pay for independent living without selling your house opens up financial flexibility and allows you to maintain homeownership. Several strategies can help you cover community costs while keeping your property as a family asset or income source.
- Use your home equity through a HELOC to access funds while retaining ownership, though carefully consider interest rates and repayment obligations
- Explore reverse mortgages if you're 62 or older, but understand that moving to independent living may trigger repayment requirements
- Generate monthly income by renting your property, accounting for maintenance costs, property management, and potential vacancy periods
- Tap into retirement accounts and investments like 401(k)s, IRAs, and brokerage accounts to fund your move with a financial planner's guidance
- Review your community's payment options and consult a financial advisor to create a personalized strategy that aligns with your long-term goals
Moving to an independent living community doesn't mean you have to sell your house. You may want to keep it for sentimental reasons, pass it down to family, or maintain financial flexibility. Fortunately, several independent living financing options can help make the move possible without giving up homeownership.
Understanding your choices for paying for independent living without selling your house can help you make a decision that fits your finances and future plans.
Ways to Use Your Home Equity
Your home equity may be one of your most valuable financial resources. A home equity line of credit (HELOC) allows you to borrow against your property's value while keeping ownership.
A HELOC provides flexibility because you can withdraw funds as needed rather than borrowing everything upfront. However, interest rates, repayment requirements, and the risk of losing your home if you cannot repay the loan deserve careful consideration.
Understanding Reverse Mortgages
Reverse mortgages are another option for homeowners age 62 and older. These loans convert home equity into available funds without requiring regular mortgage payments.
However, most reverse mortgages require the property to remain your primary residence. Moving permanently into independent living may trigger repayment, making this option unsuitable for some situations.
Before borrowing against your house, discuss the terms with a qualified financial advisor.
Renting Your House for Monthly Income
Renting your property may provide monthly income to help cover independent living expenses while allowing you to retain ownership.
This approach can be especially appealing if your house is in a desirable Keller neighborhood. However, rental income isn't guaranteed, and ownership still involves ongoing expenses.
Before becoming a landlord, consider:
- Rental income: Compare expected rent with mortgage payments, taxes, and insurance.
- Property maintenance: Budget for repairs, upkeep, and unexpected expenses.
- Property management: Consider hiring a company to manage tenants and maintenance requests.
- Vacancy periods: Set aside funds for months when the property isn't rented.
A property manager can reduce your day-to-day responsibilities, giving you more time to enjoy your new lifestyle.
Independent Living Financing Options Through Investments
Retirement savings and investments can help fund independent living without requiring a home sale.
Depending on your financial situation, potential funding sources include:
- 401(k) accounts: Establish systematic withdrawals from retirement savings.
- Traditional and Roth IRAs: Explore distributions while considering applicable tax rules.
- Brokerage accounts: Use accessible investments to supplement monthly income.
- Annuities: Receive income payments according to your contract terms.
A financial planner can help determine which accounts to draw from first while considering taxes, required minimum distributions, and long-term financial needs.
This approach may be particularly helpful when exploring how to finance independent living while preserving your house as a family asset.
Bridge Loans and Short-Term Financing
If you eventually plan to sell your house but aren't ready yet, a bridge loan may provide temporary financing.
These short-term loans generally use your property as collateral and can help cover expenses while you prepare for a future sale.
Bridge financing may allow you to move into independent living before your house sells, but it comes with important considerations. Interest rates can be higher than traditional mortgage rates, and repayment deadlines may create financial pressure if the property takes longer to sell.
Compare borrowing costs and repayment requirements before deciding whether this approach makes sense.
Senior Living Costs Without a Home Sale: Payment Options and Assistance
Understanding independent living payment methods is an important part of building your budget.
Some communities offer different payment structures, including monthly rental agreements or entrance-fee arrangements. Availability and terms vary by community.
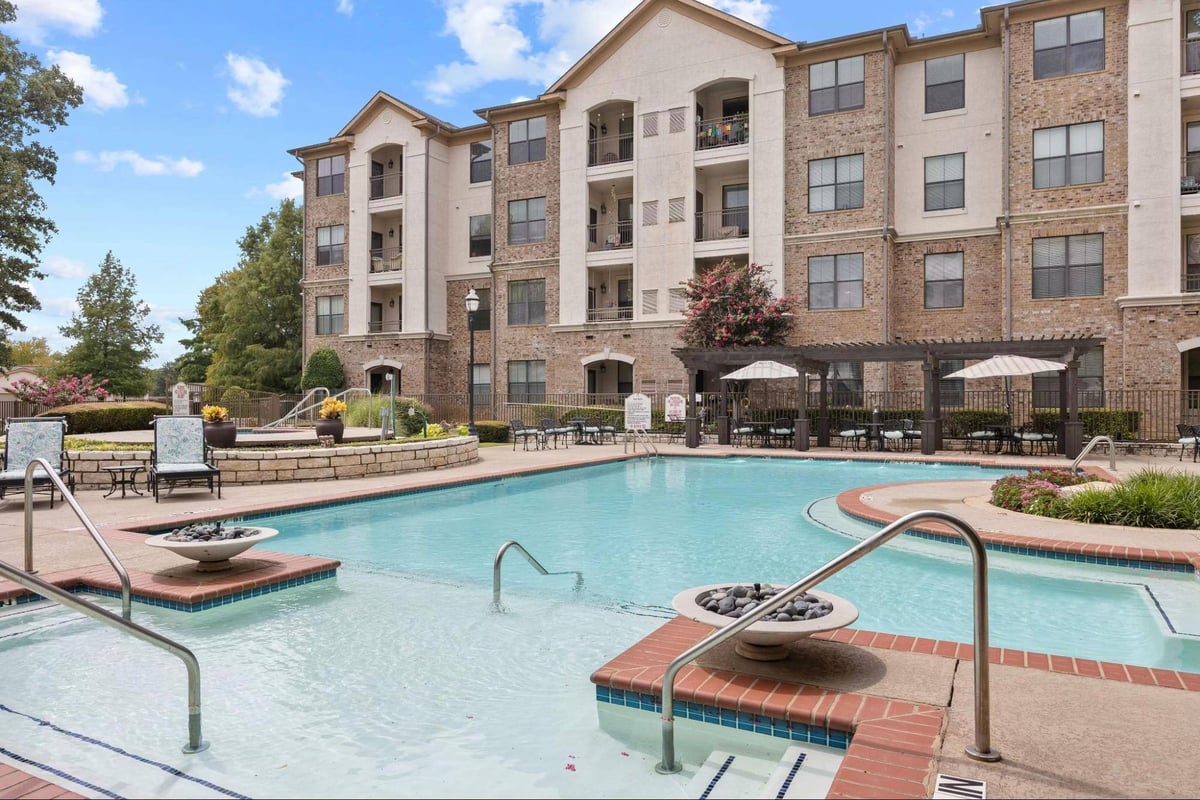
At Conservatory At Keller Town Center, residents can explore a variety of apartment home floor plans and pricing options to find a living arrangement that aligns with their preferences and budget.
When comparing senior living costs without a home sale, review the complete monthly expense rather than focusing only on the advertised rate.
Exploring Additional Financial Resources
Depending on eligibility and policy terms, additional resources may include:
- Veterans benefits: Certain benefits may provide financial assistance, although eligibility and covered expenses vary.
- Long-term care insurance: Some policies offer limited benefits, but independent living expenses generally aren't covered.
- Life insurance benefits: Certain policies allow access to cash value or other available benefits.
- Local assistance programs: Some programs may help eligible older adults with specific household expenses.
Reviewing these resources can help families explore ways of affording senior living while keeping their house.
Creating Your Personal Financial Strategy
A practical financial plan starts with understanding your income, assets, and expected monthly expenses. Compare the costs of maintaining your house with the expenses associated with independent living. Include property taxes, insurance, utilities, maintenance, and any rental management fees.
At Conservatory At Keller Town Center in Keller, TX, Active Independent Living offers a maintenance-free lifestyle centered on convenience, dining, and community connections. Residents can enjoy Sensations Dining, Impressions Housekeeping & Maintenance, and Connections Transportation, making everyday routines easier while leaving more time for personal interests.
Consider how community amenities and services may affect expenses you currently pay separately. Consulting a financial advisor or elder law attorney can also help you evaluate your options and protect your long-term financial interests.
Keeping your house while moving into independent living may be possible through rental income, investments, or other financing strategies. With a thoughtful budget, you can explore a simpler lifestyle while maintaining financial flexibility.
Schedule a tour to discover how Conservatory At Keller Town Center's Active Independent Living experience can fit your plans and discuss available pricing options.